
Business Loans and Working Capital:
Business Term Loan: Lump sum, fixed monthly payments Requirements: FICO 600+ $8K+/MO REVENUE
Business Line of Credit: For businesses that outgrew the standard tier. Max Loan $5M. Requirements: Fico 600+ $8k+/MO REVENUE
Working Capital: Same Day Options on some programs. Max loan $150K. Requirements: FICO 500+ $15K+/MO REVENUE
SBA Loan Programs:
SBA 7(a) Loan: Flexible use, Slower to close. UP to $5M. Requirements: FICO 650+ $8k+/MO REVENUE
SBA 504 Loan: Real Estate and Fixed Assets. UP to $5.5M. Requirements: FICO 680+ 0+/MO REVENUE
SBA 504 Express Loan: The Fastest SBA Tier. UP to $500K. Requirements: FICO 650+ Lower Revenue bar than 7(A) loan
SBA MICRO Loan: Startup Friendly, Minimal History Needed, UP to $50K. Requirements: FICO 575+ Minimal Revenue Required
Specialty Financing:
EQUIPMENT Financing: The Equipment itself is the collateral. By Equipment Cost. Requirements: FICO 660+ 15k+/MO REVENUE
AR INVOICE Financing: An Advance against the unpaid invoices. %of Invoice Value. Requirements: No FICO Minimum. Based on Customer Credit
PERSONAL UNSECURED Loan: For Qualified Individual borrowers. Requirements: FICO 620+
UNSECURED DOWN PAYMENT Loan: Covers the Shortfall to close. Requirements: FICO 620
The Five Tools
Sequencing matters. Best served in this order.
1. Debt Consolidation $10K TO $100K
Drops revolving utilisation below 30 percent to help move your FICO score 40 to 80 points in a single
reporting cycle, while freeing up monthly cashflow. Runs alongside gap funding, not before it.
2. Rapid Gap Funding $20K TO $120K
UNSECURED TERM LOAN STACKING
Multiple unsecured term loans stacked across multiple lenders, submitted in the order matched to your
income. No lien, no collateral.
3. 0% Credit Stacking UP TO $150K
PERSONAL AND BUSINESS
Simultaneous 0 percent card applications matched to your location and banking relationship. Liquidate to
pay invoices directly, then stack bigger on the next round.
4. HELOC UP TO $150K*
HOME OR LLC OWNED INVESTMENT PROPERTY
A revolving line against equity you already have, interest only during the draw period. FICO minimum
depends on which property secures the line.
LLC Owned Investment Property FICO 700+
Home / Primary Residence FICO 620+
5. Business Line of Credit $50K TO $250K
Tied to the strength of your operating business, not real property. Pay interest only on what you draw.
2 TO 7 YR TERM · FUNDED IN 1 TO 5 DAYS FICO 650+
3 TO 5 YR TERM · FUNDED IN 1 TO 3 DAYS FICO 680+ · $40K+/YR INCOME TYPICAL
12 TO 21 MO AT 0% · FUNDED IN 1 TO 10 DAYS FICO 690+ · INCOME NOT A GATING FACTOR
10 YR DRAW · 20 YR REPAY · 14 TO 45 DAYS
REVOLVING · FUNDED IN 1 TO 7 DAYS FICO 600+ · $10K+/MO REVENUE
REAL ESTATE LOANS:
The biggest blunder any investor can make in real estate is to shop too early for money, yet this is the most common mistake we see investors making in real estate. The rule of thumb is it’s much easier to shop for cash when you have a deal in hand and under contract.
Why? Because as long as that property is not under contract, it’s up for grabs by anyone and everyone and no lender will spend time and resources on a property that can be snatched out from under the borrower at any moment’s notice.
Putting the house under contract is an easy enough, 4-Step process.
- Step 1:Prospect and Review Potential Properties
- Step 2:Write Offers
- Step 3:Get Offer Accepted by Seller
- Step 4:Put Earnest Money in Escrow to complete the contract.
Once these 4 Steps are completed, you have a fully executed Purchase and Sale Agreement, the property is under contract, and you are ready to shop for cash. If you’re ready to move forward and receive a term sheet, then fill out the form at the bottom of the page and we will get back to you within 24 business hours.
5 Reasons Why Investors Use Private Money
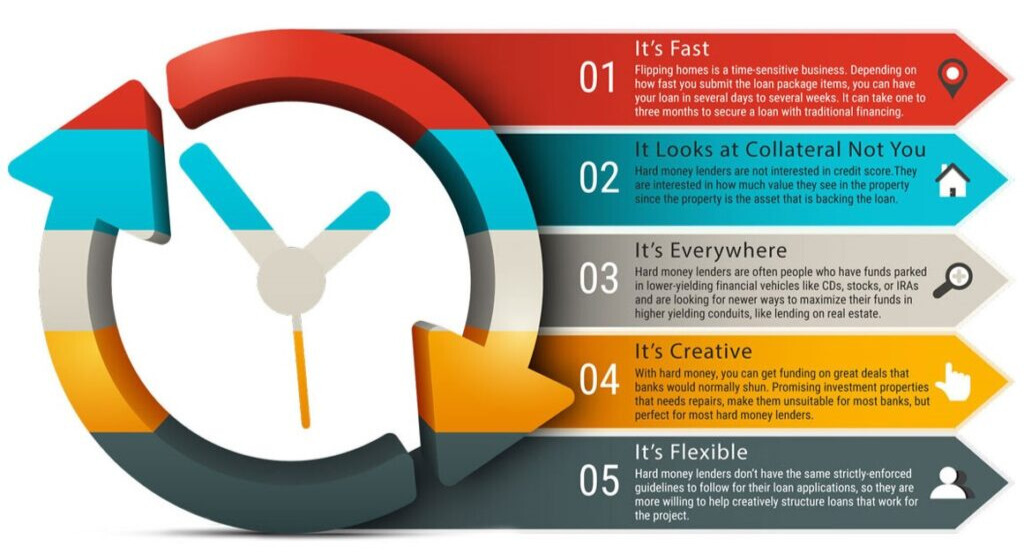
- It’s Fast: Flipping homes is a time-sensitive business. Depending on how fast you submit the loan package items, you can have your loan in several days to several weeks. It can take one to three months to secure a loan with traditional financing.
- It Looks at Collateral, Not You: Private money lenders are not interested in credit score. They are interested in how much value they see in the property since the property is the asset that is backing the loan.
- It’s Everywhere: Private money lenders are often people who have funds parked in lower-yielding financial vehicles like CDs, stocks, or IRAs and are looking for newer ways to maximize their funds in higher yielding conduits, like lending on real estate.
- It’s Creative: With Private money, you can get funding on great deals that banks would normally shun. Promising investment properties that need repairs, make them unsuitable for most banks, but perfect for most Private money lenders.
- It’s Flexible: Private money lenders don’t have the same strictly enforced guidelines to follow for their loan applications, so they are more willing to help creatively structure loans that work for the project.
Having a Private Money Lender, like Covenant Money Fund in your court gives you confidence to put properties under contract. As long as you find the no-brainer deal that fits our guidelines, do the proper due-diligence, and turn in an application. you can be rest-assured that the deal will be funded!
The first part of every successful fix and flip is finding the right real estate property. That’s why we’ve created this easy, 5-point guide to help you find the “sweet spot” deal, which can give you the best chance at making money in real estate, while safeguarding your investment.
At Covenant Money Fund we are only interested in funding projects that will give you the best opportunity at realizing success. Therefore, our criteria is centered around these 5 points:

Homes above the FHA cap are statistically more likely to experience drastic fluctuations in value and can be more susceptible to local and overall market depreciation. Homes in the 5-point realm tend to be more resilient to these influences.
WHY 1-4 UNITS?
This is important. When you invest within these parameters, you can attract a larger segment of the market, including FHA buyers. This increases your ability to appeal to more people in more demographics.
WHY PRICE YOUR HOME AT OR BELOW FHA REQUIREMENTS?
FHA loans bring home ownership into reach for first-time home buyers who might have a hard time getting approved with conventional lenders. This increases your ability to sell your property faster and broadens your ability to attract more potential buyers.
WHY A SMALLER HOME WITH NO MORE THAN 5 BEDROOMS AND 3 BATHS?
Millennials and Boomers are the two segments expected to dominate the market in the next five years. Both of these segments are looking at smaller homes: Millennials because they’re just starting out; Boomers because they’re downsizing. Candace Taylor of The Wall Street Journal wrote, “These days, buyers of all ages eschew the large, ornate houses… in favor of smaller, more modern-looking alternatives.”
WHY LESS THAN 1/2 ACRE?
Both Boomers and Millennials are looking for less upkeep: Boomers because they’re getting older and Millennials because they’re just starting out. More acreage also means more expense.
Fix & Flip Financing Built Around the Deal
A Fix & Flip Loan is a short-term, asset-based loan designed for real estate investors purchasing and renovating non-owner-occupied properties. Financing is primarily evaluated using the purchase price, renovation scope, borrower qualifications, and the property’s projected after-repair value, or ARV.
Covenant Money Fund offers Fix & Flip programs based on the strength of the borrower and the deal:
- Up to 90% of the purchase price and 100% of the renovation budget, not to exceed 65% of ARV.
- JOINT VENTURE: Up to 100% of the purchase price and 100% of the renovation budget, not to exceed 75% of ARV.
These loans are commonly used when an investor needs to close faster than conventional financing allows or when the property requires repairs before it can qualify for long-term financing. Fix & Flip Loans typically feature short loan terms, interest-only payments, and renovation funds released through construction draws as work is completed.
Unlike a conventional mortgage, approval is not based solely on personal income or whether the property is currently move-in ready. However, credit history, experience, liquidity, project scope, market conditions, and the overall strength of the transaction may still affect eligibility, pricing, and leverage.
Whether you are purchasing your first investment property or expanding an established portfolio, Covenant Money Fund will evaluate the people, property, and package to identify the program that best fits the deal.
We fund the deal. You take the credit.
DSCR Loans
Covenant Money Fund offers DSCR financing for investors purchasing, refinancing, or pulling equity from non-owner-occupied rental properties. Qualification is based primarily on the property’s rental income and cash flow rather than traditional personal-income documentation.
Our DSCR programs include:
Option 1.
Designed for investors seeking stable, long-term financing.
- Up to 80% LTV
- 30-year fixed-rate options
- Fully amortizing payments
- Purchase and rate-and-term refinance options
Option 2.
Built for investors who need more flexibility.
- Up to 80% LTV
- Adjustable-rate and interest-only options
- Flexible prepayment structures
- Long-term and eligible short-term rentals
Option 3. BRRRR
Created for investors who want to put existing equity back to work. BRRRR
- Cash-out refinance options
- Up to 75% LTV
- Financing terms up to 30 years
- Funds may be used to grow or improve your rental portfolio
Programs may be available for single-family rentals, two-to-four-unit properties, condominiums, townhomes, and eligible planned-unit developments.
While DSCR loans generally do not rely on tax returns for income qualification, borrowers may still be required to provide bank statements, proof of reserves, credit documentation, lease information, an appraisal, and other underwriting items.
Wholesale & Deal-Specific Funding
EMD (Earnest Money Deposit) Funding · Covers your deposit so your own capital stays free $2K TO $25K+ TYPICAL
NO FICO MINIMUM · DEAL BASED, NOT INCOME
Transactional Funding (Double Close) · Same day A to B to C close, same title company 100% OF PURCHASE PRICE
NO FICO MINIMUM · NONE REQUIRED
Gator Lending (Private Gap Funding) · Private capital behind a hard money loan, not Gap Funded’s own stack VARIES BY DEAL
FICO 680+ · 150%+ COLLATERAL ON SEPARATE ASSET
More Doors. More Cash Flow. More Freedom.
Programs, rates, leverage, and terms are subject to change. All loans are subject to credit approval, property appraisal, lender guidelines, and final underwriting.
More Types of Deals Covenant Money Fund

Loan Terms
1. Max Loan Amount: Just Bring Us Your Deal! No cap on the loan amount if the numbers make sense. Rest assured; we will help you get it done. Call us today for more details. Covenant Money Fund has funding solutions from $30,000 up to the FHA Cap in the county where the investment property is located and can provide additional lending solutions based on the property you have under contract and type of loan needed.
2. Rates: Current rates start at 7.5% annualized interest with an origination fee from 0-5%, and no prepayment penalties. (Rates are based on credit score but credit score does NOT determine loan approval.)
3. Loan Term: 6 Months to 2 Years for a fix & flip. 30 Years for a buy & hold or refinance. One loan approved per applicant until proven track record
Please complete the form below, and we’ll get in touch with you within 24 business hours to provide a no-obligation term sheet for your Real Estate Deal and for your Business Loan questions.
Copyright © 2026 Covenant Money Fund – All Rights Reserved.